Christian Kontz

Christian Kontz

Assistant Professor of Finance, University of Notre Dame
Faculty Fellow, Notre Dame Institute for Global Investing

Hi, I am an Assistant Professor of Finance at the University of Notre Dame. I received my PhD in Finance from Stanford Graduate School of Business in 2026. My research sits at the intersection of empirical corporate finance and asset pricing. I study how delegated asset management, the growth of passive investing, and emerging trends like ESG shape firms' decisions and real economic outcomes.


Working Papers

The Real Cost of Benchmarking (with Sebastian Hanson)

FESE De La Vega Prize '26 FIRS PhD Paper Prize '25 SFS Cavalcade PhD Student Award '25
@techreport{kontzhanson2024, title={The Real Cost of Benchmarking}, author={Kontz, Christian and Hanson, Sebastian}, type={Working Paper}, institution={University of Notre Dame}, year={2024}, url={https://ssrn.com/abstract=4884602} }

Abstract

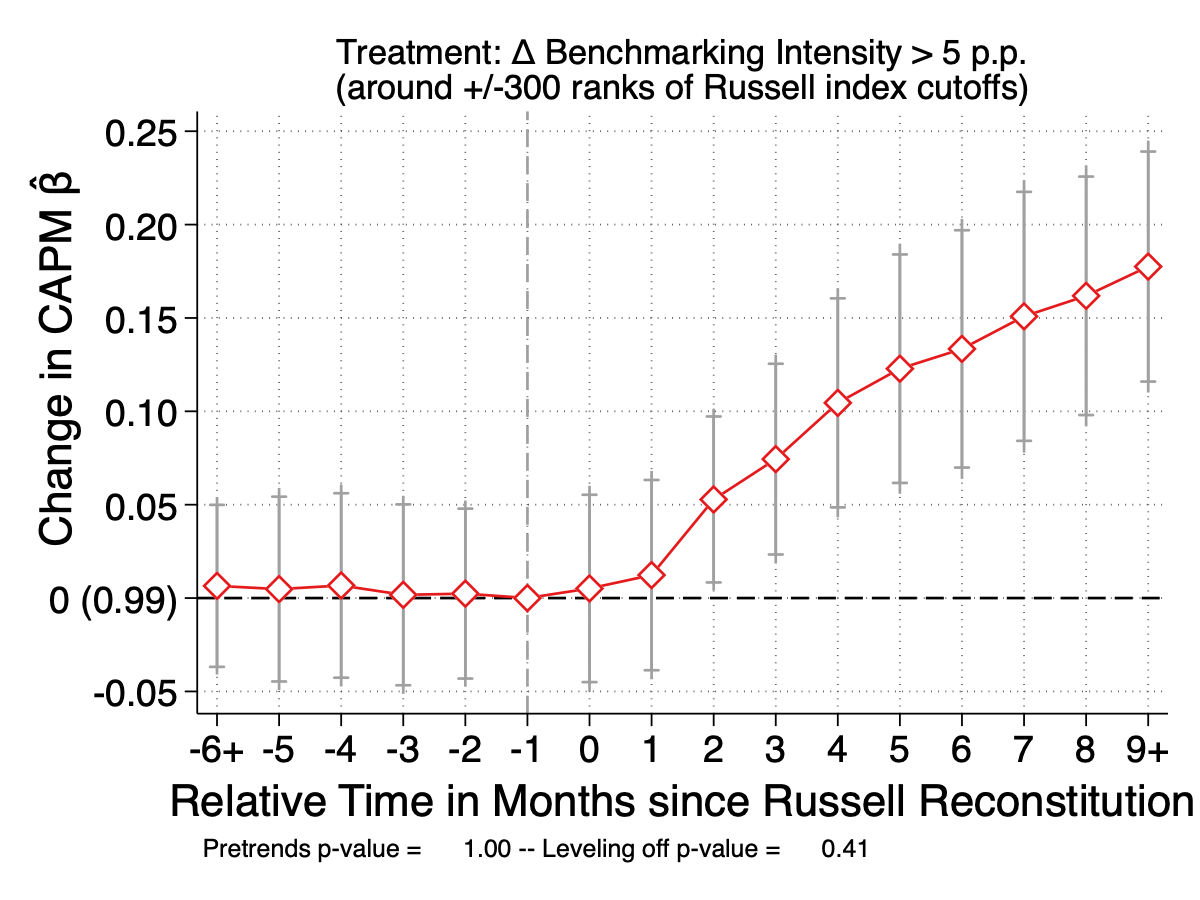
Benchmark-linked capital flows increase firms' CAPM βs, thereby raising managers' perceived cost of equity and reducing investment. Using exogenous variation from Russell and S&P 500 reconstitutions, we show that inclusion in a benchmark stock index increases a stock's CAPM β. Managers interpret the higher β as a higher cost of equity and reduce investment. Consistent with this mechanism, benchmark inclusion also raises the perceived cost of equity among stock analysts and regulators. Industries with larger increases in βs due to benchmarking have accumulated less capital over the past two decades. Benchmark-induced changes in the cross-section of CAPM βs do not cancel out but affect aggregate investment because higher βs fall on many firms with high investment elasticities, while lower βs benefit a few large but inelastic firms.

Seminars: Federal Reserve Bank of New York, Notre Dame Mendoza, NYU Stern, UT Austin McCombs, Boston College Carroll, Ohio State University Fisher, Bocconi University, University of Virginia Darden, National University of Singapore, Einaudi Institute, Copenhagen Business School, University of Maryland Smith, Singapore Management University

Conferences: EUROFIDAI Paris December Meeting 2026*c, FiFi 2026, EFA Annual Meeting 2026, AFA Annual Meeting 2026, SFS Cavalcade 2025, FIRS 2025, Johns Hopkins Carey Finance Conference, Four Corners/FMRC Conference on Indexing, Investment Company Institute, Northeastern University Finance Conference 2025, UIC Finance Conference 2025c
(* scheduled, c co-author)

Awards: FESE De La Vega Prize 2026, SFS Cavalcade PhD Student Award, FIRS Conference 2025 Prize for PhD Students, Shortlisted for Brandes Center Prize

Media: Bloomberg's Matt Levine Money Stuff, Frankfurter Allgemeine, UC San Diego Brandes Center
Do ESG Investors Care About Carbon Emissions? Evidence From Securitized Auto Loans

Winner of the 6th Annual Sustainable Finance in Fixed Income Research Competition '26 UN PRI Best PhD Paper '25 FIRS PhD Paper Prize '24 GRASFI Best PhD Paper '24 Myron Scholes PhD Prize '24 Citations: 12

@techreport{kontz2023esg, title={Do ESG Investors Care About Carbon Emissions? Evidence From Securitized Auto Loans}, author={Kontz, Christian}, type={Working Paper}, institution={University of Notre Dame}, year={2023}, url={https://ssrn.com/abstract=4357312} }

Abstract

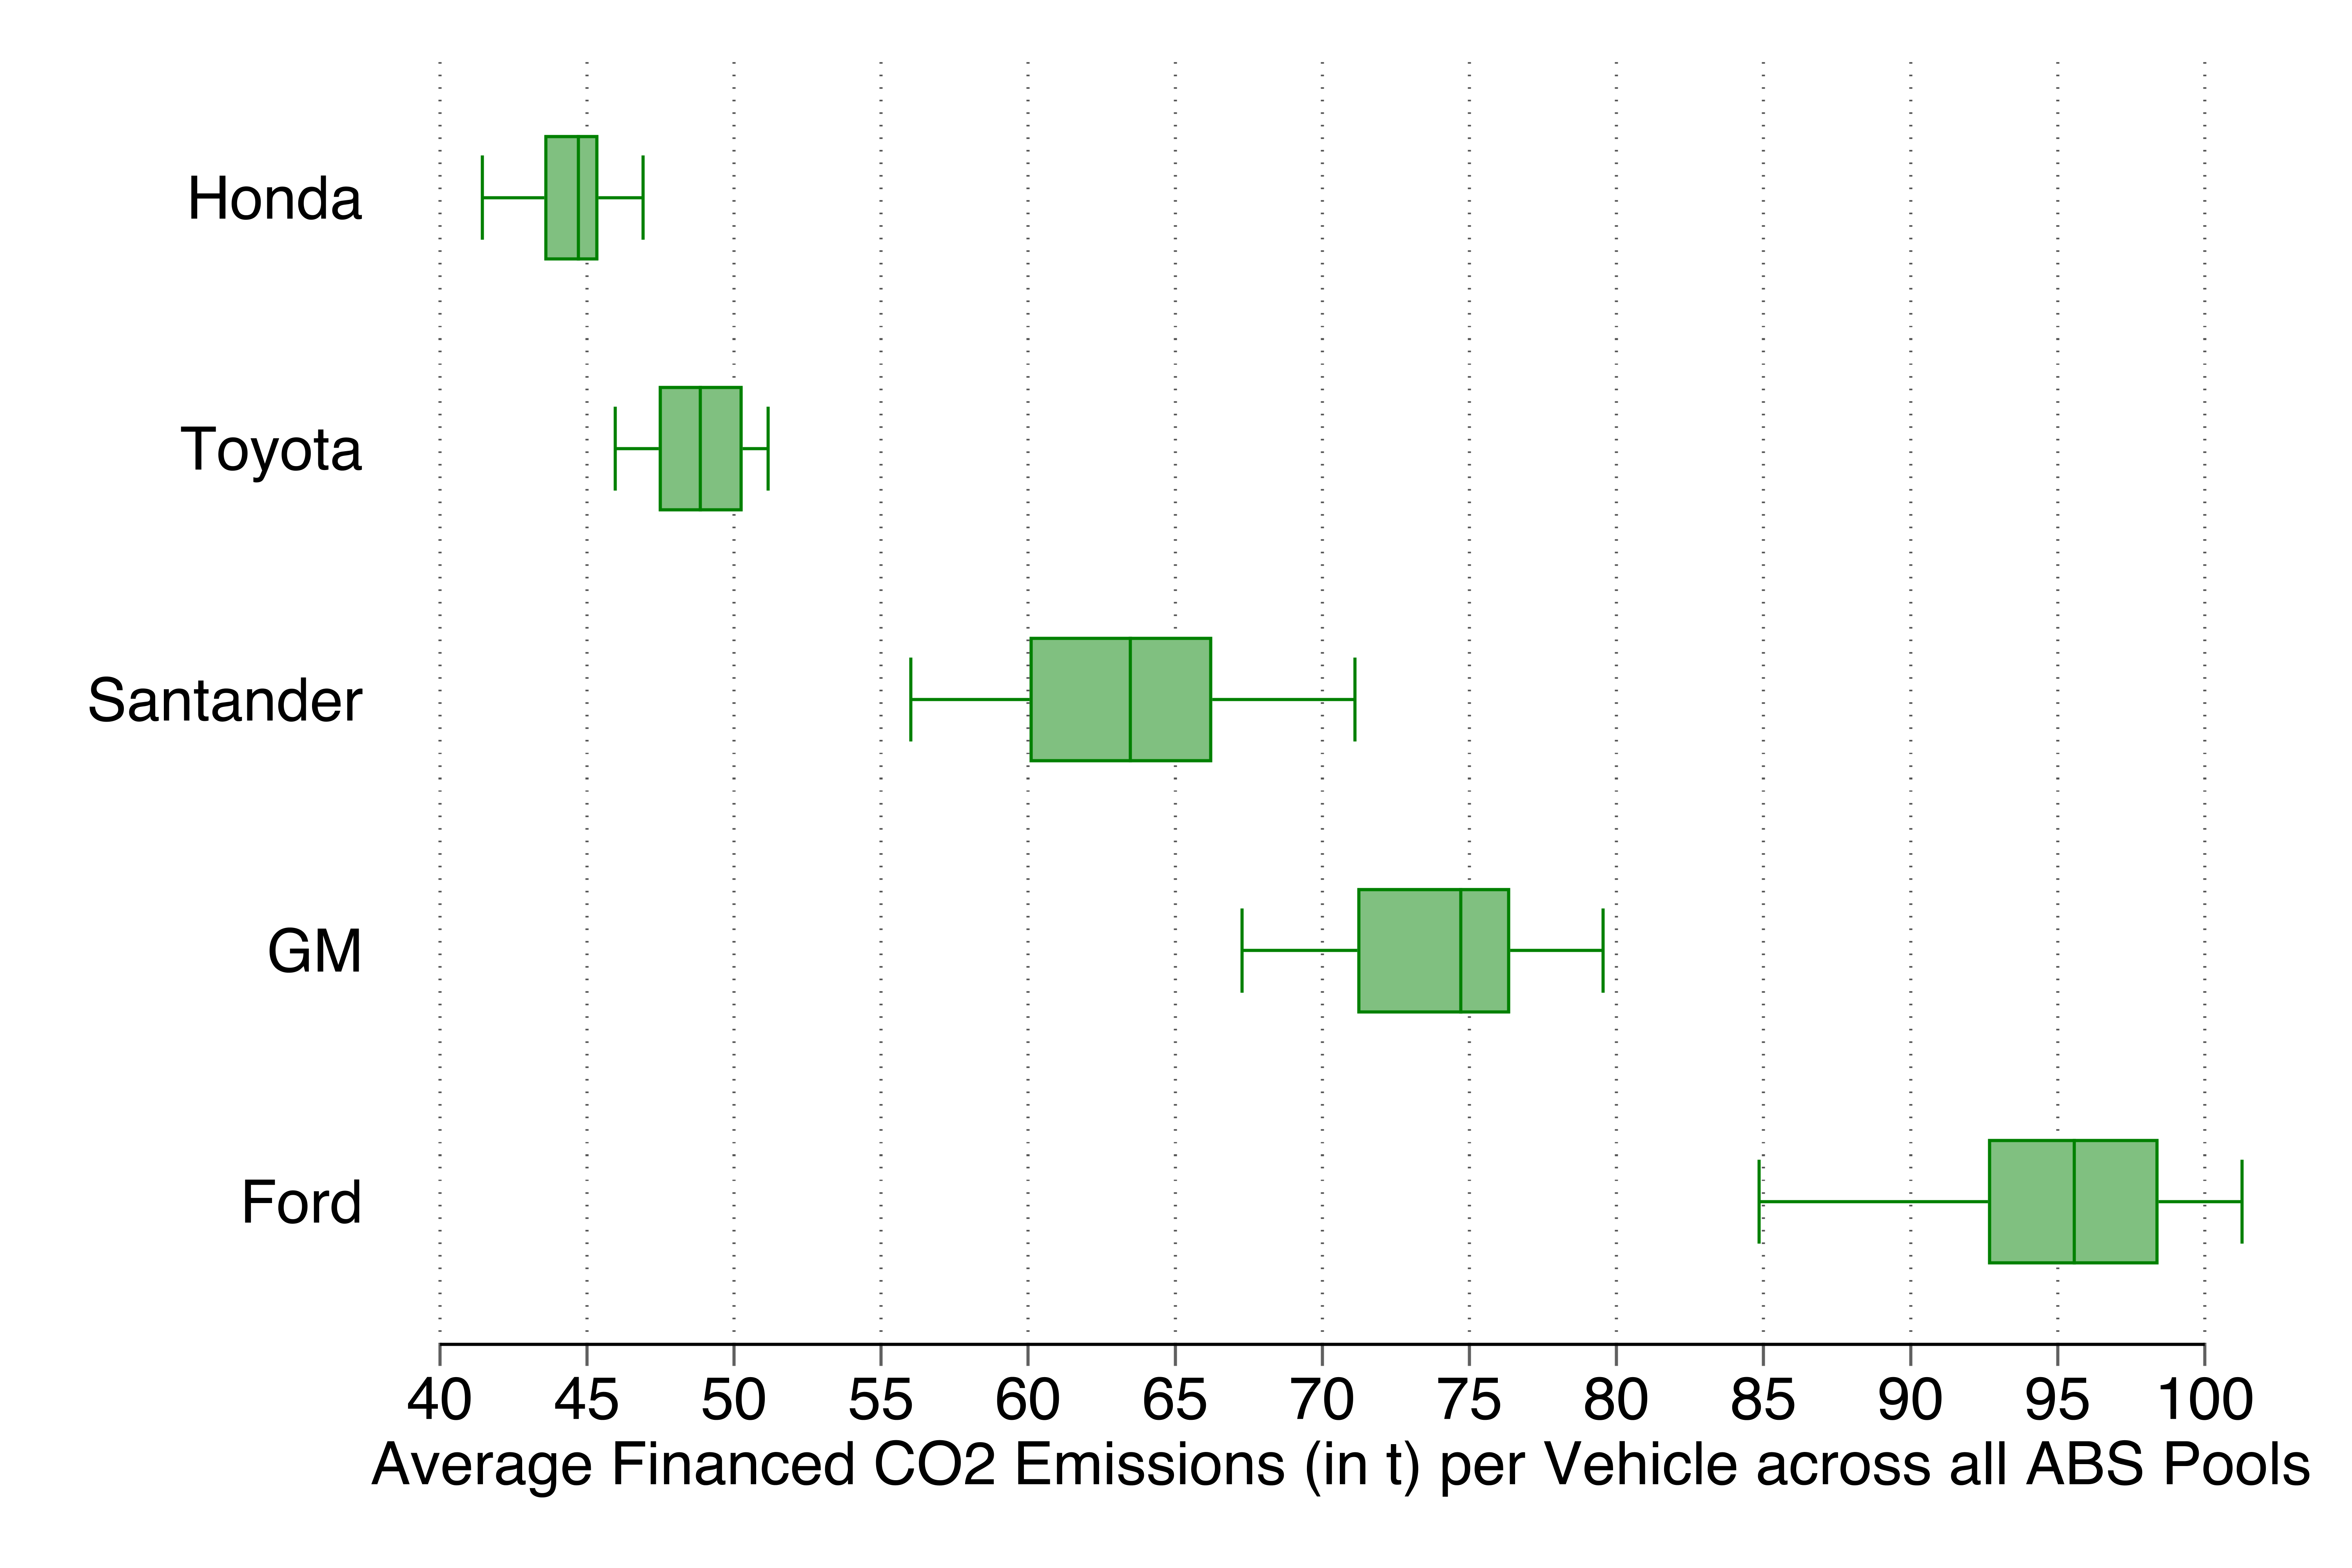
This paper documents that ESG preferences in fixed income markets affect real outcomes through securitization. I find that higher ESG scores lower funding costs for auto loan securitizations and that captive lenders pass through these savings to consumers: a 9 basis points ESG funding advantage translates into a 21 to 33 basis points lower consumer interest rate. The high pass-through is driven by an increased probability of receiving a subsidized interest rate (e.g., 0% financing). Lower consumer borrowing costs increase loan demand by up to 4.9%. Yet because issuer ESG scores are weak proxies for financed CO2 emissions, the same mechanism reduces the cost of capital for high-emission vehicles. A subjective-beliefs model can explain how investors who intend to price emissions but implement this via ESG scores lower the cost of capital of high-emission vehicles.

Conferences: FIRS Conference 2024, OU-RFS Climate and Energy Conference 2024, GRASFI Conference 2024, SoFiE Conference 2024, CEPR-ESSEC-Luxembourg Conference on Sustainable Financial Intermediation, Harvard Climate Economics Workshop, UC Santa Cruz

Awards: Winner of the 6th Annual Sustainable Finance in Fixed Income Research Competition (FIASI), UN PRI Best PhD Student Paper Award 2025, FIRS Conference 2024 Prize for PhD Students, GRASFI Conference 2024 Best PhD Paper Award, Myron S. Scholes PhD Prize 2024

Work in Progress

From Markets to Meters: How Index Investing Affects Utility Rates

Horizontal stacked bar chart of the net annual resource transfer by family income quintile, in $ million, split into electricity and gas, residential and commercial/industrial. The bottom four quintiles lose between about $205 million and $413 million a year each; the top quintile gains about $1,370 million.

Abstract

This paper shows that the growth of index investing raises the prices households pay for electricity and gas. Under cost-of-service regulation, regulators use CAPM βs to set utilities’ allowed returns on equity. Using Russell index reconstitutions, I show that greater index-linked ownership raises utilities’ βs. In rate cases between 1998 and 2018, regulators pass these increases through to allowed returns. To assess whether these higher allowed returns reflect a higher cost of equity, I develop an equilibrium model in which index flows raise measured βs without changing cash-flow risk. The model shows that allowed returns exceed the returns investors require. Consistent with this implication, I find that higher βs and greater index-linked ownership increase utilities’ market-to-book ratios. The resulting transfer from utility customers to shareholders is regressive. Households without stock ownership pay higher bills without sharing in the gains, and low-income households bear the largest consumption-equivalent welfare losses.

Presentations: Advances in Cost-of-Capital Regulation Workshop*, SUNY Binghamton, Wabash River Finance Conference 2026, German Economist Abroad Annual Meeting (UHH)
(* scheduled)

ESG Induced Capital Misallocation: is ESG Doing Good by Doing Well?

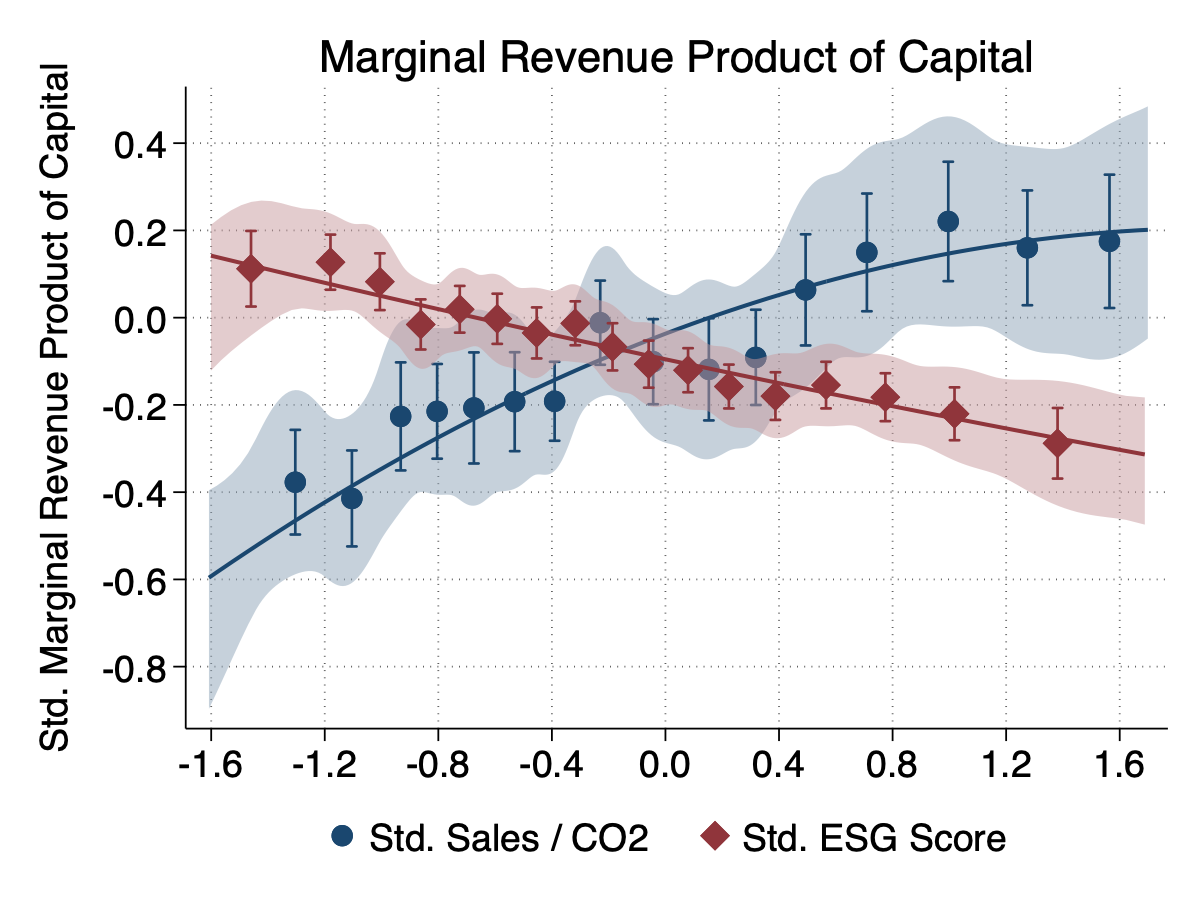
Binned scatter plot showing that the marginal revenue product of capital rises with a firm's sales per ton of CO2 emitted and falls with its ESG score.

Abstract

This paper studies the impact of environmental, social, and governance (ESG) investing on the real economy. Using within industry-year variation, I find that 1.) firms with high ESG ratings have low marginal revenue products of capital (MRPK), while, 2.) firms with high sales per tCO2 emission have high MRPKs. This suggests that reallocating capital to firms with high ESG ratings lowers allocative efficiency while reallocating capital to greener firms increases it. Motivated by these facts, I estimate a dynamic investment model featuring convenience yields on ESG assets and a CO2 externality to explore the implications of ESG investing for capital misallocation and climate change mitigation.

Media Coverage

Bloomberg

Matt Levine's Money Stuff — All Public Companies Are Alike

Frankfurter Allgemeine

Der Sonntagsökonom — Die ETF-Falle

UC San Diego Rady School of Management

The Brandes Center — Roundtable Summary

Tools & Resources

CAPM β Simulator

Simulate how excess comovement from passive fund flows shifts CAPM βs across the cross-section of stocks. Adjust the number of stocks, correlation structure, and index-specific comovement shocks to see the effect on equilibrium βs.

Launch Simulator →

Academic Journal Editors Map

A searchable database and map of nearly 1,000 (associate) editors across top economics, finance, and accounting journals.

Open Map →

FIN 30600 — Investment Theory Tools

A suite of twelve interactive apps built for my Investment Theory course at Notre Dame: volatility and fee drag, market depth and price impact, two-asset diversification and the efficient frontier, CAPM/SML and OLS β estimation, an anomaly lab, duration and bond pricing, Black–Scholes, and a live Keynesian beauty-contest game students play in class.

Open Tools →

Seminar Schedule Briefing Skill for Claude

A Claude skill that turns a seminar-day meeting schedule into a one-page landscape PDF briefing. For each attendee it compiles a career timeline, research interests, frequent co-authors, editorial roles, and current working papers.

View on GitHub →